Understanding Takaful at Sun Life Malaysia Takaful
At Sun Life Malaysia Takaful, we provide Shariah-compliant protection solutions designed to help individuals and families achieve greater financial security with confidence. As a licensed Family Takaful operator, we are committed to delivering solutions that uphold the principles of Shariah while addressing the evolving protection needs of our customers. Our operations are guided by transparency, fairness and mutual cooperation, supported by a robust Shariah governance framework.
Our takaful solutions are built on the principles of ta'awun (mutual assistance) and tabarru' (donation), which form the foundation of the takaful model. Through these principles, participants contribute to a common fund with the intention of helping one another during times of need, fostering a spirit of shared responsibility and collective support.
In conducting our takaful business, Sun Life Malaysia Takaful ensures that its operations and activities comply with Shariah principles and avoid elements prohibited under Shariah such as riba (interest or unjustified gain), gharar (excessive uncertainty) and maisir (gambling). This commitment reflects our dedication to providing protection solutions that are both financially resilient and Shariah-compliant.
Through our customer-centric approach, we strive to make Shariah-compliant protection accessible and relevant to the diverse needs of Malaysians. By combining sound takaful practices with a commitment to service excellence, we aim to support our customers in protecting what matters most at every stage of life.
How Takaful Operates at Sun Life Malaysia TakafulAt Sun Life Malaysia Takaful, our family takaful business is conducted based on Shariah-approved contractual arrangements and a robust governance framework that promote mutual assistance, transparency and fairness among participants. The diagram below illustrates the transaction flow throughout the takaful lifecycle.
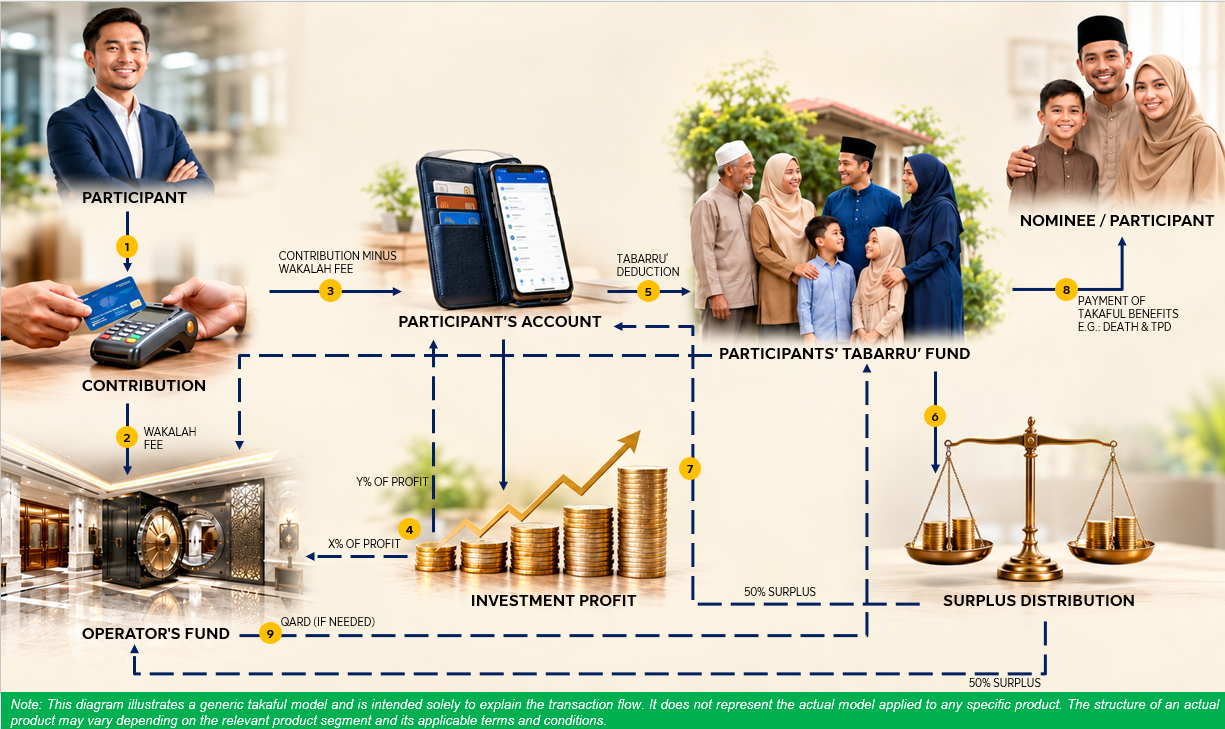
- Participant pays contribution to their takaful certificates and appoint Sun Life Malaysia Takaful as an agent under the Wakalah contract to manage the contribution on the participant’s behalf.
- A portion of the contribution is deducted as a Wakalah fee to cover distribution costs and operational expenses associated with managing the takaful business.
- The balance of the contribution, after deduction of the Wakalah fee, is credited to the Participant’s Account, which is owned by the participant.
- Funds held in the Participant’s Account are invested in Shariah-compliant investments under the Mudarabah contract. Any investment profits are distributed between the participant and the takaful operator based on the applicable profit-sharing ratio.
- A portion of the contribution is allocated to the Participants’ Tabarru' Fund under the Tabarru' contract. The fund is collectively owned by participants and serves as the source of financial assistance for eligible claims.
- Any surplus remaining in the Participants’ Tabarru' Fund after claims, reserves, expenses and repayment of any qard provided by the takaful operator will be distributed to eligible participants and the takaful operator.
- 50% of the distributable surplus is allocated to eligible participants, while the remaining 50% is allocated to Sun Life Malaysia Takaful.
- When a covered event occurs, benefits are paid from the Participants’ Tabarru' Fund to the participant or beneficiary in accordance with the certificate terms.
- If the Participants’ Tabarru' Fund experiences a deficit, Sun Life Malaysia Takaful may extend an interest-free loan (qard) to the fund to ensure that claims obligations can continue to be met. Any qard provided is repaid from future surpluses of the fund.
Gharar refers to excessive uncertainty or ambiguity in a contract, which is prohibited under Shariah.
Hibah is a voluntary gift transferred without consideration and is frequently used in family takaful for benefit nomination, allowing takaful proceeds to be gifted to a nominated beneficiary upon death, subject to Shariah rulings and applicable laws.
Maisir means gambling or speculative gain based on chance, which is prohibited under Shariah.
Mudarabah is a profit-sharing partnership in which one party provides the capital and the other manages it; in certain takaful models, investment profits are shared between participants and the operator according to a pre-agreed ratio, while losses are borne by the fund.
Qard is an interest-free loan extended as a benevolent act and may be provided by the takaful operator to a takaful fund experiencing a deficit, with repayment made from future surpluses without interest.
Riba refers to interest or any unjustified gain, excess, or benefit in financial transactions that is prohibited under Shariah.
Shariah refers to the principles and rules of Islamic law which guide takaful business and operations.
Tabarru' is a voluntary donation given without expectation of return, whereby participants irrevocably dedicate part of their contribution to the takaful fund to mutually assist other participants.
Ta'awun means mutual cooperation or assistance for the common good and is the ethical principle underpinning takaful, where participants collectively share risks and support one another.
Wakalah is an agency contract in which one party appoints another to act on its behalf; in takaful, the operator acts as an agent managing the takaful fund in return for an agreed Wakalah fee.